Cargo Insurance vs. Carrier Liability for Importers
Cargo insurance and carrier liability are not the same protection. Carrier liability depends on the transport contract, applicable law, the responsible stage, exclusions, and proof of loss; cargo insurance is a separate contract with its own insured value, covered risks, deductible, exclusions, and claim conditions.
An importer should not assume that a door-to-door or DDP price automatically provides full-value insurance. Ask for the insurance arrangement and evidence in writing before the cargo is released.
What Is the Practical Difference?
| Question | Carrier liability | Cargo insurance |
|---|---|---|
| Where does protection come from? | The transport contract and applicable liability rules | A shipment-specific or open insurance policy |
| Is full commercial value automatic? | No | Only if the policy, valuation, limits, and claim are accepted under its terms |
| What must be proved? | Responsibility, stage of loss, condition, value, and compliance with notice requirements may matter | A covered event, insured interest and value, compliance with packaging and claim conditions |
| Are there exclusions or limits? | Usually; they depend on the contract and transport regime | Yes; exclusions, deductibles, limits, commodities, routes, and packaging conditions vary |
| What document should you ask for? | Bill of lading, air waybill, delivery record, and applicable service terms | Policy, certificate, or other written evidence identifying the actual coverage |
The answer for a specific loss depends on the documents and facts. This guide does not replace the carrier’s terms, an insurance policy, or professional legal and insurance advice.
Does DDP Include Cargo Insurance?
Not automatically. DDP describes responsibilities in the sales transaction, but the DDP label alone does not prove that shipment-specific cargo insurance was purchased for the buyer.
The International Chamber of Commerce explains that Incoterms® rules allocate costs, risks, and obligations between seller and buyer. In the current rules, CIF and CIP are the terms that include an express seller obligation to arrange insurance; the parties can still agree on additional insurance under other terms. Review the official ICC Incoterms® 2020 resources and make the actual coverage part of the written sales and transport records.
If a freight quote says “insurance included,” ask what policy applies, who is insured, which route and cargo are declared, what value is covered, and what exclusions or deductible apply.
What Should You Confirm Before Buying Coverage?
- Exact insured party and party entitled to make a claim
- Commodity, packaging, quantity, and declared or insured value
- Origin, destination, modes, warehouses, transshipment, and final delivery included
- Start and end points of coverage
- Covered causes of loss or damage
- Exclusions for fragile goods, batteries, used goods, moisture, rust, poor packaging, delay, or unattended storage
- Deductible, limit, valuation basis, and currency
- Required packing, inspection, survey, notice, and document conditions
- Claim contact, reporting deadline, and evidence required
The U.S. International Trade Administration notes that international agreements may limit carrier liability and advises exporters to consider cargo insurance according to the terms of sale. Its cargo insurance overview also distinguishes the insurance arrangement from the transport method.
How Do Packaging and Insurance Affect Each Other?
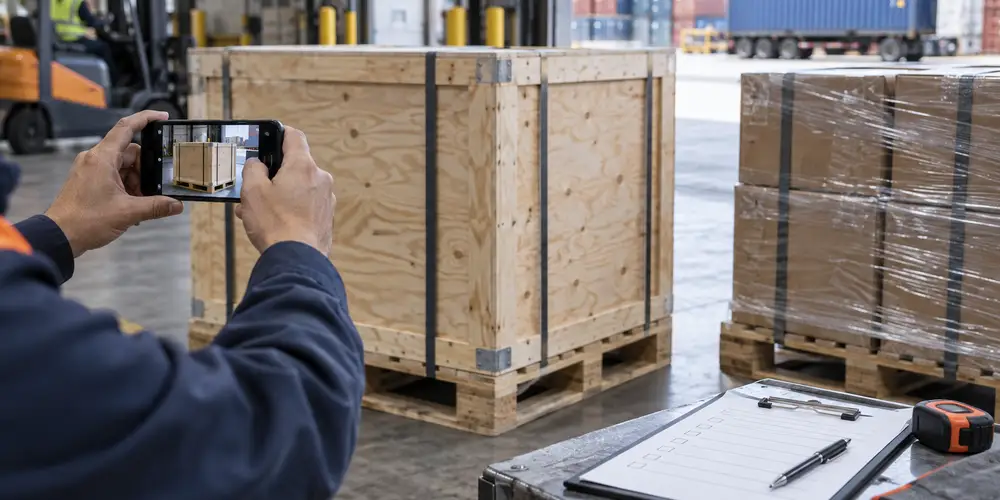
Insurance does not make unsuitable packaging acceptable. A policy may contain packaging, inherent-vice, commodity, or condition exclusions. For bulky or fragile cargo, keep written evidence of the packing method, final dimensions, piece weights, external condition, and any warehouse reinforcement.
Use our bulky commercial cargo packaging guide to prepare the handling facts before requesting coverage. The packaging provider and insurer should review unusual, fragile, high-value, or top-heavy pieces rather than relying on a generic carton or crate label.
What Evidence May Be Needed After Loss or Damage?
Act according to the applicable policy and transport terms. A practical evidence file may include:
- Commercial invoice and packing list.
- Bill of lading, air waybill, or other transport record.
- Insurance policy or certificate.
- Origin packing and condition photos.
- Delivery receipt with exceptions noted when visible and permitted.
- Photos taken before the cargo is moved, repaired, or discarded.
- Notice to the carrier, forwarder, insurer, or surveyor within the required time.
- Repair estimate, replacement evidence, survey, or disposal instructions when requested.
Do not discard damaged cargo or packaging until the responsible parties confirm the next step. A signed clean delivery receipt can make later fact-finding more difficult, but the effect depends on the actual contract and claim.
When Is a Separate Insurance Review Especially Important?
- High-value cargo relative to the freight charge
- Fragile furniture, sanitary fixtures, glass, stone, or precision equipment
- Used machinery or goods whose condition is difficult to establish
- Long multi-stage routes with consolidation, transshipment, or storage
- Cargo requiring special temperature, moisture, orientation, or handling conditions
- Delivery sites where unloading equipment or access is uncertain
Insurance availability is not guaranteed for every commodity, value, route, or packaging method. Confirm acceptance before booking and do not advertise a policy as “full coverage” without reading the actual terms.
Add Insurance to the Quote Review
Use our freight quote checklist to record cargo value, packaging, route, and delivery facts. Then request a shipment review and ask separately whether cargo insurance is available, what written evidence will be provided, and which conditions apply.